Author Archives: GK Strategy

Conservative Party Conference: Can Kemi Badenoch’s ‘Right Way’ Win Back Britain?

This year’s conference season saw one of the clearest ideological divides in British politics for some time. The prime minister delivered a speech that many on the left had long wanted to hear, making the case for a more active and interventionist state. In Birmingham, Kemi Badenoch offered an equally unapologetic defence of Thatcherism.

The Conservative leader’s speech gave a sense that the party is finally off life support and up for the fight, with a renewed appeal to the shires through promises of tax cuts that will undoubtedly energise the Tory core vote. At the same time, Badenoch sought to challenge Reform UK on questions of values and integrity. Clearly adored by her party members, she remains behind in the polls and continues to fight for attention from the country.

More significant than any individual announcement was the moral case set out in The Right Way, Badenoch’s conference policy document, and echoed throughout her speech. Almost every policy proposal was rooted in a belief in personal responsibility and the value of individual endeavour. Badenoch argued that individual effort is not only the source of economic prosperity but also of human fulfilment and opportunity. In that sense, her speech was about more than policy. It was a battle of ideas, with Badenoch presenting conservatism as a competing vision ‘for the soul of the country’.

The headline-grabbing policy announcement was Badenoch’s pledge to abolish inheritance tax on family homes and raise the amount an individual can pass on tax-free to £500,000. Under the proposals, a couple would be able to leave their main residence to direct descendants free from inheritance tax, alongside a further £1 million of assets to other beneficiaries. Long criticised by many on the right as Britain’s least fair tax, inheritance tax is often portrayed as a form of double taxation, applying to assets accumulated from income that has already been taxed.

Badenoch also identified the eventual abolition of inheritance tax as a long-term ambition. Critics argue, however, that the benefits would be concentrated among the wealthiest and not ‘ordinary’ families. The Institute for Fiscal studies estimated that the wealthiest 1% of estates, worth £2.1 million or more, would receive around half of the gains from full abolition. Some also worry that the proposal could encourage older homeowners to remain in larger properties, limiting the availability of family-sized homes.

The Leader of the Opposition also argued that too many people are being written off by a welfare system that discourages work. Her reforms would remove access to out-of-work benefits immediately after school or university, introduce ‘back to work’ cards for long-term claimants, and require those able to work to engage with employment programmes. Badenoch aims to couple these welfare reforms with plans to halve the jobs tax for under-25s and repeal Labour’s Employment Rights Act.

Badenoch said that cutting the welfare bill would help fund higher defence spending, something that was notably absent from Burnham’s conference speech. Central to this was a £10 billion commitment to build ‘Britannia Shield’, an integrated UK air and missile defence network. The proposal would initially focus on protecting critical national infrastructure and military bases before being expanded to cover the UK mainland and British territories overseas. However, with the programme expected to be delivered over ten years, it represents a long-term ambition rather than a rapid build-out.

The proposal is more ambitious than the government’s current plans, having previously identified missile defence as a priority while allocating less than £800 million to the capability over four years. This comes despite a recent commons Defence Committee report warning that the UK has ‘next to nothing’ in place when it comes to missile defence, particularly against the growing threat posed by drones.

Despite the non-nonsense tone of Badenoch’s speech and the long list of policy commitments unveiled at conference, all of it ultimately depends on the Conservatives returning to power. With Badenoch ruling out an electoral pact with Reform UK and the party still polling below its performance at the 2024 general election, the central question remains whether voters are willing to give the Conservatives another hearing after fourteen years in government.

Steve Brine, GK’s Strategic Adviser and former health minister said: ‘What struck me was the attempt to give the Conservatives a clearer organising argument: that Britain’s problems stem from weak growth and an overextended state, and that the answer is greater economic freedom, lower taxes and firmer choices about public spending. The speech also sought to present Kemi as someone prepared to make the case for a distinct Conservative identity and one that her party feels wholly comfortable with. In that, the two main parties are in lock-step. The test will be whether that argument can be turned into a credible and coherent programme for government.’

Robert Halfon, GK’s Strategic Adviser and former education minister said: ‘Kemi Badenoch leaves conference with her leadership secure and her party more united than it has been for years. The direction is clear: firmly Conservative, and clearly distinct from Reform. Skills are part of that offer. Badenoch put apprenticeships in her leader’s speech, and the plan to move money from poor-value degrees into apprenticeships gives the Education team a concrete policy to drive forward. Employers will now want to see it costed and funded.’

Labour Party Conference: Burnham’s plan to make Britain ‘Hope Again’

GK’s Lauren Atkins shares her reflections from attending Labour Party Conference.

As September drew to a close, party members, politicians, journalists and public affairs professionals once again descended on Liverpool for the annual Labour Party Conference. The third since Labour took office in 2024, this year’s gathering was the first with Andy Burnham as Prime Minister, setting the stage for a party looking to turn the page on recent political instability.

There was a palpable buzz around this year’s conference. The atmosphere was one of renewed optimism and a desire for clearer direction, reflected in the presence of Burnham’s new cabinet colleagues and junior ministers, who packed out fringe events and receptions to engage with party members and businesses. There was a clear effort to reconnect Labour with its sense of purpose and build excitement around the government’s next chapter.

Under the banner of “Hope Again”, Burnham’s first conference speech as Prime Minister provided the focal point. Promising to “break with the direction of the past forty years”, he criticised deindustrialisation, deregulation, privatisation, austerity and Brexit, setting out a vision in which the state takes a more active role in public services, economic renewal and tackling the cost of living. The speech received at least eleven standing ovations from delegates in the main conference hall, underlining the enthusiasm among party members for a clear, long term political vision for the UK.

The policy announcements were wide-ranging. Burnham committed to establishing a National Care Service in the next parliament, transforming the state pension triple lock from 2030, and launching a commission on electoral reform. He also signalled a renewed focus on the UK’s long-term relationship with the EU, promised legislation to enable the public ownership of water companies, and announced plans to remove VAT from electricity bills from the beginning of October, develop a national energy plan and establish Great British Grid. On housing, he reaffirmed plans for the biggest council housebuilding programme since the post-war era, alongside measures to support first-time buyers and reform leasehold. Internationally, he pledged to put AI at the centre of the UK’s G20 presidency next year.

Taken together, these commitments offered a clearer articulation of the government’s ambitions and helped sustain the conference’s sense of momentum. Yet, while the enthusiasm in Liverpool was unmissable, the government faces a tight timetable to convince the wider electorate that its vision can deliver. With the next general election less than three years away, the challenge will be to turn the optimism of “Hope Again” into tangible improvements for households and businesses, particularly those facing persistent cost-of-living pressures.

Yesterday’s long-term commitments – with the most significant policy changes not expected until 2030 – were certainly valuable for Burnham in setting out his stall and establishing a sense of direction, but they will do little to reassure voters unless progress is also felt in the near term. The upcoming Budget will be an early test of how the government intends to balance its ambitious programme with the realities of public spending and the immediate economic pressures facing the country.

Burnham has given Labour members renewed reason to feel energised about the future. The conference had a genuine sense of optimism and purpose, but the real test lies beyond Liverpool docks. The coming months will determine whether that enthusiasm can translate into effective government, and whether “Hope Again” can become more than a conference slogan.

What Great British Grid means for Britain’s electricity network

In his first address to Labour Party Conference as prime minister, Andy Burnham set out plans for a new government-backed body, Great British Grid (GBG), as part of a wider effort to address high energy costs, accelerate infrastructure delivery and support economic growth.

For investors and businesses, the government’s plans for GBG are unlikely to represent a fundamental change to the ownership or operation of Britain’s electricity network. The Department for Energy Security and Net Zero has said that GBG will ‘complement, rather than replace’ the companies already responsible for operating the electricity system, with the role of existing network operators remaining unchanged. Instead, the focus is on changing how future transmission infrastructure projects are developed and delivered.

GBG will operate as a branch of Great British Energy (GBE) and will participate in bids for future transmission projects. Rather than incumbent network operators automatically developing new infrastructure, projects could be awarded through a competitive process involving bids from GBG, existing network companies and private investors. The government argues that increasing competition in this way will help speed up grid expansion, support economic growth and reduce the costs of network investment that are ultimately passed on to consumers through energy bills.

The scale of GBG’s involvement will depend on the funding available to it. GBE was allocated £8.3 billion of capital funding for this parliament, although a proportion of that funding has already been committed to other priorities, including support for small modular nuclear reactors. While the final allocation to GBG has yet to be confirmed, it is likely to be small compared with the scale of investment required across the electricity network. Planned transmission investment during the 2026-31 regulatory period alone is expected to total around £70 billion, with substantial further investment required throughout the 2030s.

The use of competition to deliver transmission infrastructure is not entirely new. The Competitively Appointed Transmission Owner (CATO) regime, introduced under the Conservative government in 2023, was designed to open parts of the transmission network to competitive procurement. GBG therefore builds on an existing framework for competition, while giving the state a more direct role in bidding for future transmission projects.

The government has also announced reforms that would allow businesses to construct their own grid connections rather than waiting for network operators to undertake the work. Ministers hope this approach will accelerate the delivery of energy projects, industrial developments and AI data centres in the UK.

While these reforms may help reduce some delays, many industry groups continue to argue that the planning and consenting system remains one of the biggest barriers to faster infrastructure delivery. The success of the government’s approach is therefore likely to depend not only on changes to grid connections, but also on whether wider planning reforms can shorten approval times for major energy projects.

Please contact Brett Morton via brett.morton@gkstrategy.com if you would like to discuss the government’s energy reforms in more detail.

View from the US: A Blue Wave is taking form

Erin Caddell of GK Strategy’s American partner Anchor Advisors examines the shifting US midterm landscape and the implications of a potential Democratic resurgence.

Like a surfer looking out at the ocean for the next big swell, US political observers are seeing signs of a gathering political “Blue Wave” – a potential shift in control of the House of Representatives and/or the Senate to Democrats in the midterm elections on 3 November. At this point, it is difficult to tell whether the wave will be big or small, and in the rapidly shifting seas of American politics, it could dissipate before it hits the shore. But US-focused investors and corporates should start paddling now to position themselves for the policy changes likely to occur.

As with most US political analysis these days, the midterm election outlook begins and ends with one man: President Trump. Arriving at the halfway point of the president’s term, midterms are often viewed as referenda on the incumbent administration’s progress. And with Trump dominating his party and the political debate as few have, midterm campaigns have been more focused on Trump than on the individual House and Senate candidates.

Here, the news is not good for Trump and the GOP. Continuing a trend we’ve noted in this column in recent months, Trump’s approval rating continues to grind lower due to high fuel prices driven by the unpopular US war with Iran, sticky inflation, and more recently, by a reacceleration of a trade war with Canada. An FT poll released on 6 September is indicative of the trend of recent US voter surveys: The poll of 1,914 registered voters found that 33% approved of Trump’s performance at the end of August, down from 39% in May. Equally troubling for the GOP, the survey found that independent voters’ approval of the president dropped from 32% in May to 26% in August.

Trump’s sagging popularity is being felt on the campaign trail. In the House, Republicans hold a slim majority of 218-214, meaning Democrats need to flip three seats to seize control. 270towin, an election forecaster, pegs 215 House seats as leaning Democratic, and 201 Republican equivalents, with 19 toss-ups in the 435-member body.  Since 1946, the incumbent party has lost an average of 25 House seats in the midterms. Betting markets ascribe a 90% likelihood of a House flip in November.

In the fight for the Senate, with Republicans holding a 53-47 edge, Democrats need to win a net four seats to gain control (the Vice President breaks ties). The Democrat candidate is leading in the latest polls for GOP-held seats in Alaska, Maine, Iowa, North Carolina, Ohio and Texas, according to RealClearPolitics, though the margins are within a point or two in several, and a couple of Democrat-controlled Senate seats are also close. Betting markets peg odds of a Democratic Senate flip at 62-3%, up from 30% a year ago.

A lot can change in two months. But the data begs the question: What would it mean for US-focused investors and corporates for Democrats to win one or both houses of Congress in November? We focus here on two sectors: healthcare and renewable energy:

Healthcare. The healthcare and health insurance sectors have faced stiff headwinds throughout the second Trump Administration. The One Big Beautiful Bill (OBBB) – the centerpiece of the Republican legislative agenda in the first half of Trump’s second term – approved US$911 billion in spending cuts in the Medicaid health-insurance program for the poor over 10 years (some 15% of projected spending before the bill’s passage) and tightened eligibility requirements. Trump’s health secretary, Robert F. Kennedy Jr., has also pursued an anti-vaccine agenda that has hurt large pharmaceutical companies as well as primary-care physicians who administer vaccines to young children.

Democrats would not gain the ability to overturn administrative decisions even if the party wins the House or Senate in November. But through the appropriations process, a Democrat-led congressional chamber would dig out an old DC playbook: delay and live to fight another day. Democrats would attempt to delay the mandated spending cuts and tougher eligibility requirements for Medicaid recipients, many of which are not scheduled to come into effect until 2027. Democrats would also push back through budget tactics and oversight hearings against RFK Jr.’s moves to water down vaccine mandates and appoint anti-vaccine members of government health advisory panels. Beneficiaries could include hospitals (which receive substantial revenue from serving Medicaid recipients), Medicaid-focused insurers, primary-care physicians’ practices and drug manufacturers.

Renewable Energy. It is a worthwhile debate whether healthcare or renewable energy has been a bigger punching bag for Trump 2.0. We’ll give the nod to renewables, as not even health providers have been paid by the government not to provide their service. The Trump Administration has taken this unusual step, offering to pay more than US$2 billion to offshore wind developers sponsors to stop and invest in fossil-fuels projects instead. The Administration reported it approved new oil and gas leases on federal lands at a pace 55% greater in 2025 than in the last year of the Biden Administration in 2024. Yet the advantages of renewable development over fossil fuels – notably lower costs and faster speed to market – have meant that renewable production has still been growing despite the Trump Administration’s stance. The U.S. Energy Information Administration (EIA) reported that total U.S. energy production grew 3.4% y/y in 2025, with natural gas production increased by 4%. Renewable energy production rose 3%, equal to the growth in crude oil output, with both solar and wind setting new records (see below). Despite Trump’s constant anti-renewable, pro-fossil-fuels rhetoric, 61% of Republicans told Pew Research Center in 2025 they support more solar power (77% for all respondents), while 48% favor more wind (68% overall).

This bipartisan base of support could lead to improved market conditions for renewables firms under a Democrat House and/or Senate. As part of broader negotiations over the federal budget or on raising the debt limit, Democrats could push to restore tax credits for renewables projects passed during the Biden Administration in the Inflation Reduction Act (IRA) that the Trump Administration and the GOP-controlled Congress have reversed or limited thus far in Trump’s second term. Democrats would also use their investigative powers in Congress to scrutinise the payments the Trump Administration has made to halt offshore wind developments. Ultimately, market demand may lead policy: The new data centers necessary to power the AI boom are expected to increase total U.S. electricity demand by 5-10% by 2028, according to estimates by the University of California’s Lawrence Laboratory. As loyal Westminster Unwrapped readers know, the data-center boom has been met by a sudden public backlash across the U.S. (see our August 2026 note “Can’t buy me love: American public opinion turns against data centers – what’s next?”). But even if actual data-center construction is half that of projected, the U.S. will need significantly more renewables capacity to meet demand even if oil and gas development proceeds apace.

If Republicans rebound and hold both houses of Congress in November, the healthcare and renewables sectors would face a challenging policy landscape, but one no more hostile than the one they have managed through since January 2025. But a small blue wave could materially improve the operating environment for sectors out of favor thus far in Trump’s second White House stint, even better if a big one crashes to shore.

The future of flight: Beyond Visual Line of Sight operations

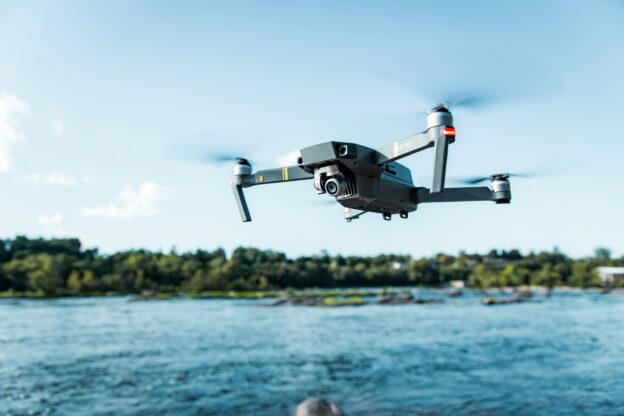
One of the main regulatory barriers to the successful commercial application of drones is the restrictions on routine Beyond Visual Line of Sight (BVLOS) operations. Many of the most commercially significant uses of drone technology require operators to fly beyond their direct line of sight, including delivery services, infrastructure inspection, surveying and mapping, and the monitoring of energy and transport networks. Enabling routine BVLOS operations is therefore critical to allowing drone services to operate at scale. This will be crucial to unlocking the full economic contribution of drones which, according to , could be worth £45 billion to the UK economy by 2030.

The UK has succeeded in funding and running trials of BVLOS operations, though these have yet to translate into a regulatory framework that enables routine operations at scale. In 2023, the CAA selected , spanning use cases from the delivery of pathology samples between hospital laboratories in London to infrastructure inspection. These trials have begun to pave the way for increased BVLOS operations, with additional London hospitals joining an expanded drone delivery service in early 2026. Operational data from the initial trial showed cost savings of 28% and a 98.4% reduction in CO2 emissions per delivery compared with conventional courier methods. This demonstrates the significant commercial and environmental benefits that BVLOS operations can provide and highlights the potential for wider adoption if the regulatory framework enables these services to move from individual trials to routine, scalable operations.

It is possible to apply to the CAA for operational authorisation for BVLOS flights using UK SORA (Specific Operations Risk Assessment), but this remains difficult to achieve in practice. To gain approval, operators must demonstrate that a specific operation can be conducted safely, meaning that authorisation may need to be sought for materially different operations or operating environments. While this approach can enable defined activities, such as regular deliveries between two hospitals, it can be time- and cost-intensive for businesses seeking to operate across multiple routes or locations that may change depending on the specific use case The publication of a SORA general operations template in August 2026 provides operators with a clearer and more standardised structure for developing the documentation required for an application. However, operators must still develop the relevant operational procedures and supporting evidence for their proposed activities, meaning that securing authorisation remains a time- and cost-intensive process. As a result, securing individual operational authorisations is not equivalent to a regulatory framework that allows routine BVLOS operations at scale, and this limits the ability of operators to scale their services rapidly.

There is a clear ambition across government and the CAA to enable routine BVLOS operations. The Regulatory Innovation Office (RIO) has been working with the Department for Transport (DfT), the Health and Safety Executive (HSE) and the CAA to address regulatory barriers to BVLOS operations. This has already resulted in several changes. A single, standardised SORA risk assessment has been introduced to reduce approval times for complex operations; the CAA is developing a , up from the previous 90-day period, providing greater certainty for longer-term operations; and its has been expanded to enable more operations in low-traffic environments, such as around power lines. While these changes operate within the existing system of approvals for individual operations, they represent incremental steps towards making BVLOS flights easier and more commercially viable. However, further reform will be required to move from facilitating individual operations towards a framework that enables routine BVLOS services to be deployed at scale.

To further scale BVLOS operations, the CAA has set out a , which charts a path towards routine and scalable BVLOS operations across the UK by 2027. Rather than pursuing a single major regulatory change, the CAA is adopting a ‘learn and evolve’ approach that will progressively move operators from segregated or restricted airspace towards integration with other airspace users as regulation, technology and operational evidence develop. The roadmap identifies three pathways for commercial operations. The first expands operations in Atypical Air Environments, such as around railways, power lines and wind turbines, where the risk of encountering crewed aircraft is comparatively low. The second focuses on integrating low-level BVLOS operations below 500 feet in urban areas, initially through restricted corridors before moving towards shared and uncontrolled airspace that can accommodate multiple operators. The final pathway is fully integrated BVLOS, enabling longer-distance operations such as middle-mile logistics, emergency services and offshore infrastructure inspection to operate alongside other airspace users. The CAA is aiming to have operations in controlled airspace underway by 2027, with operations in uncontrolled airspace beginning in 2028.

While this is a positive signal that the CAA wants to break down this regulatory barrier, it is important for the drone sector to engage closely with both the CAA and the government to ensure that the roadmap is delivered and enables routine BVLOS operations across all of these areas. It will also be important to build greater awareness among parliamentarians of the economic benefits of drones, which will make them more likely to scrutinise progress on this issue and to apply further pressure on the government and the CAA to ensure that there are routine and scalable BVLOS operations. Coordinated engagement with regulators, government and parliamentarians will be important in ensuring that the roadmap creates a regulatory environment that supports the commercial growth of the sector.

As parliament returns under the new Andy Burnham-led government, the drones sector has an important opportunity to firmly place the development of a supportive regulatory framework on the government’s agenda and build political momentum behind the reforms needed to enable routine BVLOS operations. At GK, we have launched the UK Drones Alliance, which will do exactly this by bringing together businesses from across the sector to speak with a coordinated voice to government, regulators and parliamentarians. The Alliance will provide a platform for the sector to demonstrate the benefits of drone technology and advocate for action to tackle the regulatory barriers constraining growth, enabling the industry to scale.

If you would be interested in hearing about our next UK Drones Alliance event, which we are hosting in partnership with the Department for Transport, or to discuss this policy area in more detail, please contact jacob.walsh@gkstrategy.com